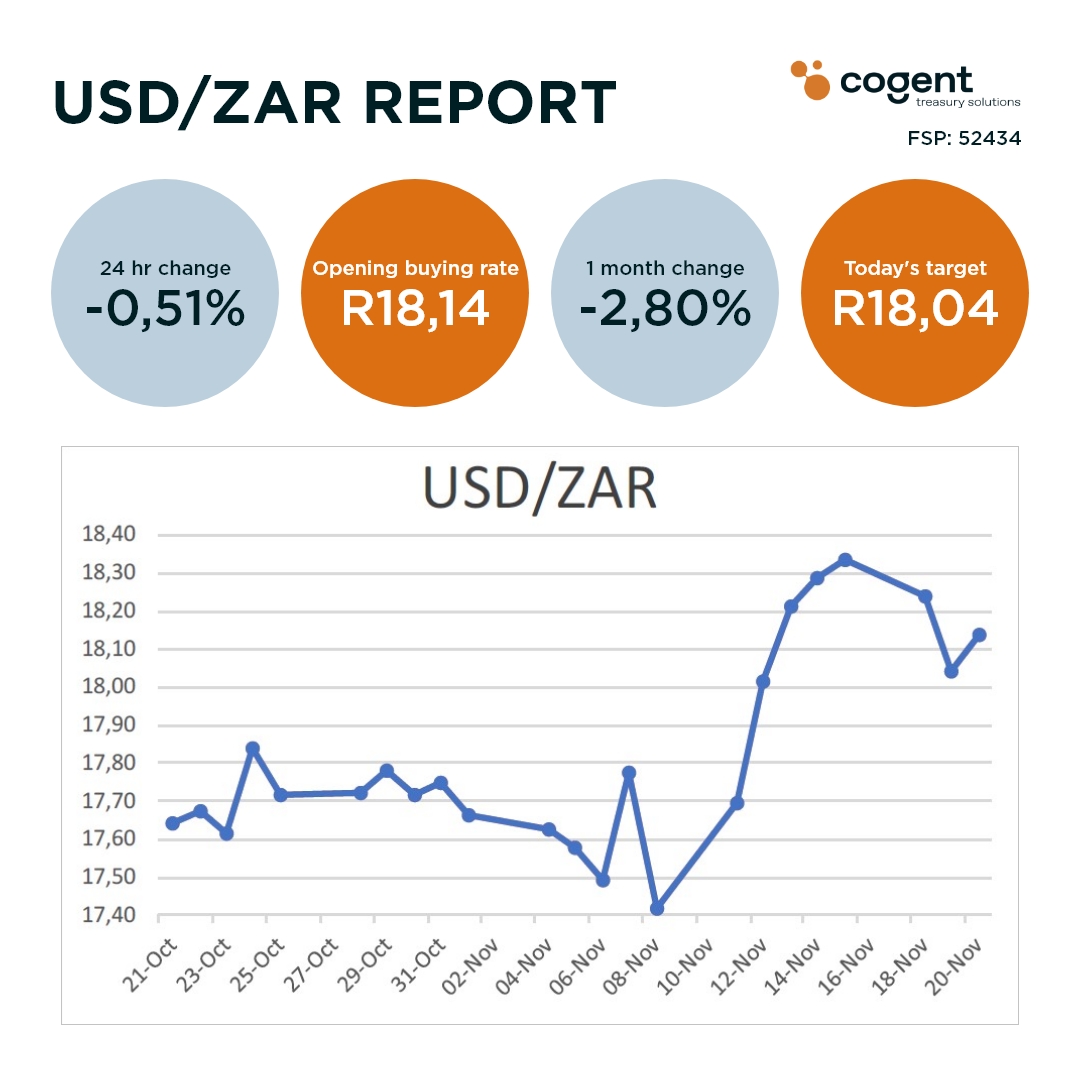
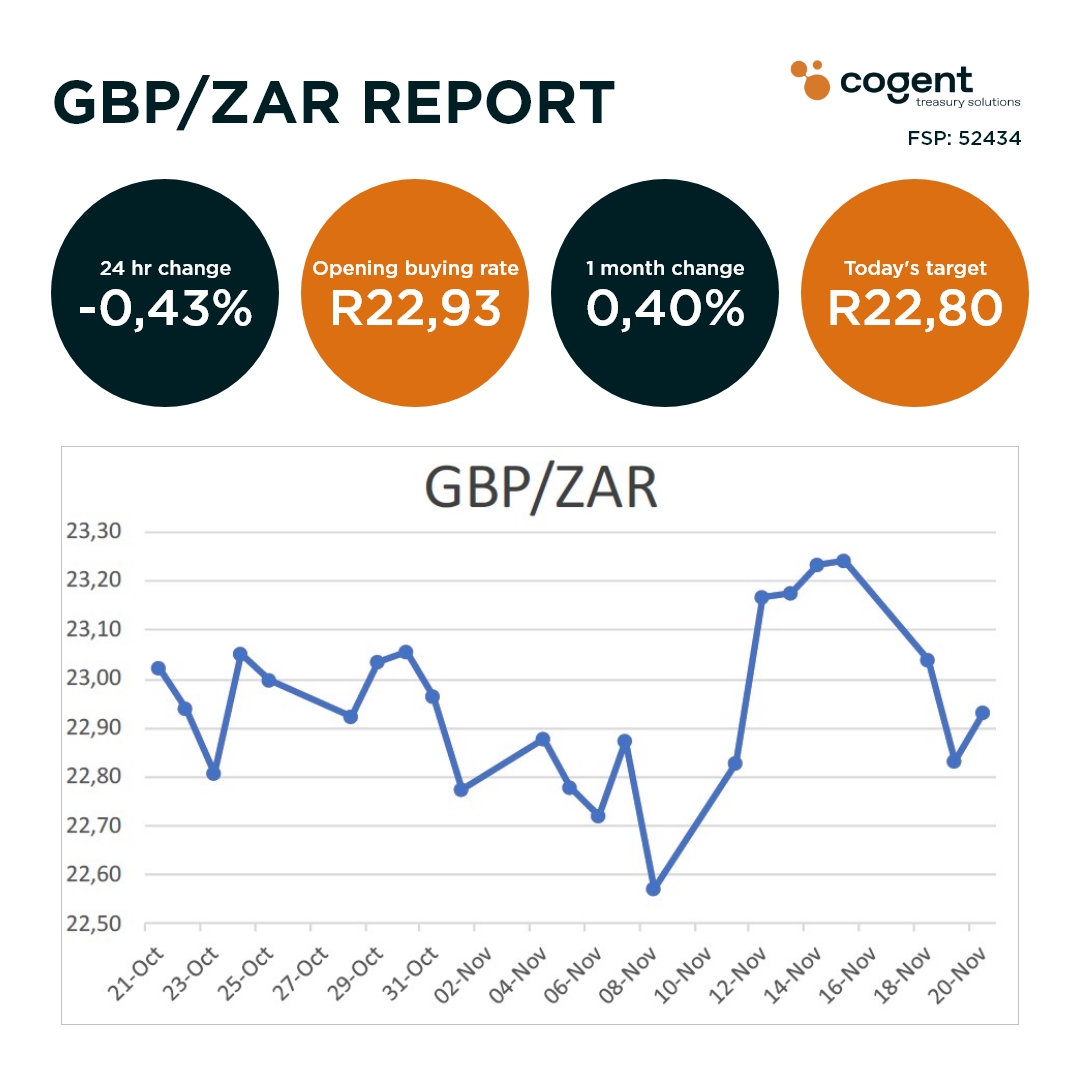
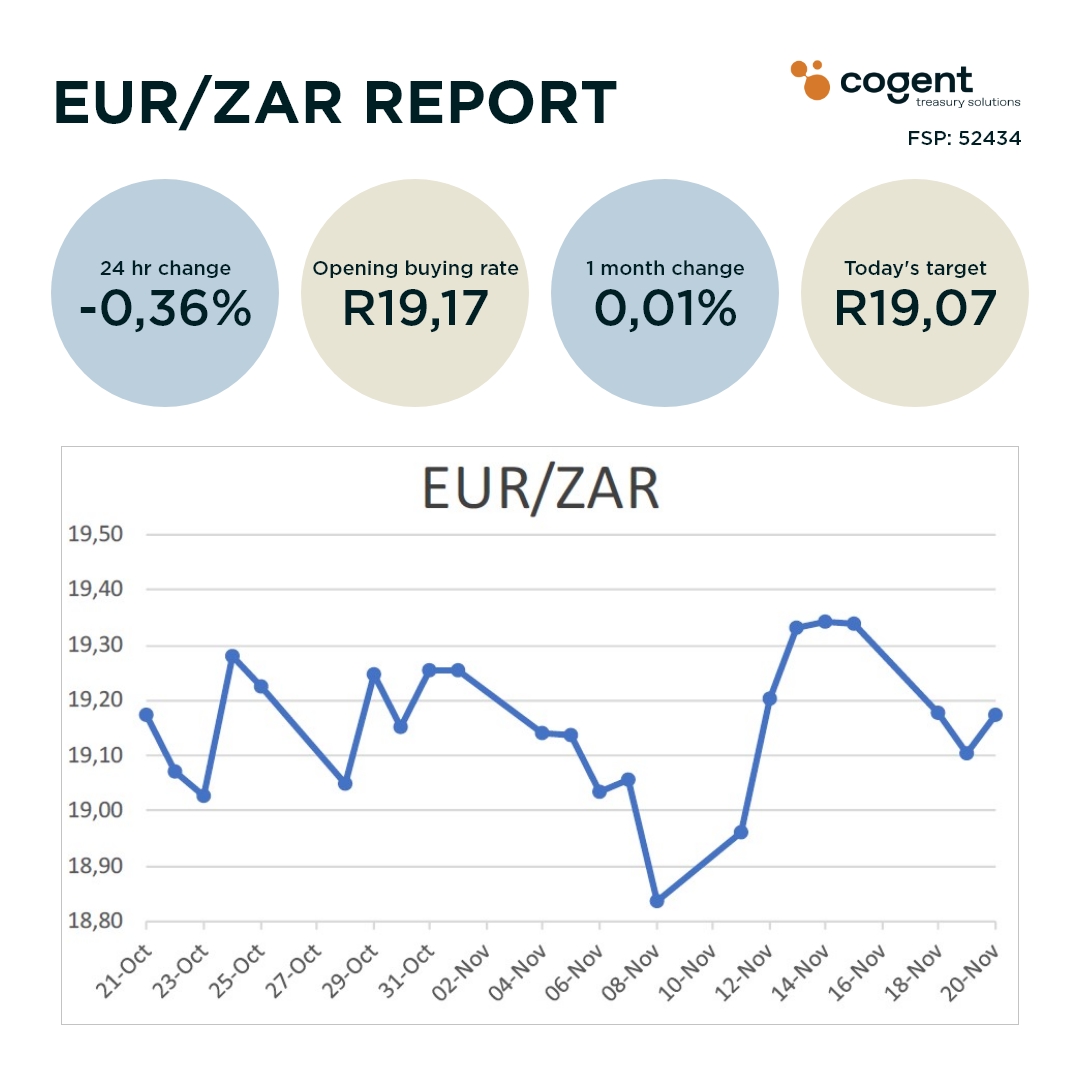
The Rand opened weaker against all the majors this morning.
Ukraine’s recent attack on Russia with ATACMS missiles has rapidly increased geo-political tensions as Russia warns this attack has marked a “new phase of the Western war”. Additionally, President Putin has approved an updated nuclear doctrine, threatening the possibility of nuclear war. The increased risk aversion will have investors rushing to safe-haven assets and will be contributing to the weaker ZAR.
Today, at 10:00, we have the release of South Africa’s CPI inflation figures, followed by the SARB interest rate decision tomorrow at 15:00. The SARB is expected to cut interest rates by 25 basis points, but today’s inflation data could influence this decision.
Todays Events:
UK CPI Inflation (YoY) at 09:00 – Expected to be 2.2% compared to previous months 1.7%. A higher-than-expected result can be seen as positive for the GBP.
German PPI (MoM) at 09:00 – Expected to be -0.1% compared to previous months -0.5%. A higher-than-expected result can be seen as positive for the EUR.
South African CPI Inflation (YoY) at 10:00 – Previous months result was 3.8%. A higher-than-expected result can be seen as positive for the ZAR.
South African Retail Sales (YoY) at 13:00 – Previous months result was 3.2%. A higher-than-expected result can be seen as positive for the ZAR.